What is a digital assets investment fund?


As in other asset classes, the crypto market has investment funds too. A crypto investment fund is a collective investment structure in which participants buy shares in a fund rather than the underlying assets themselves.
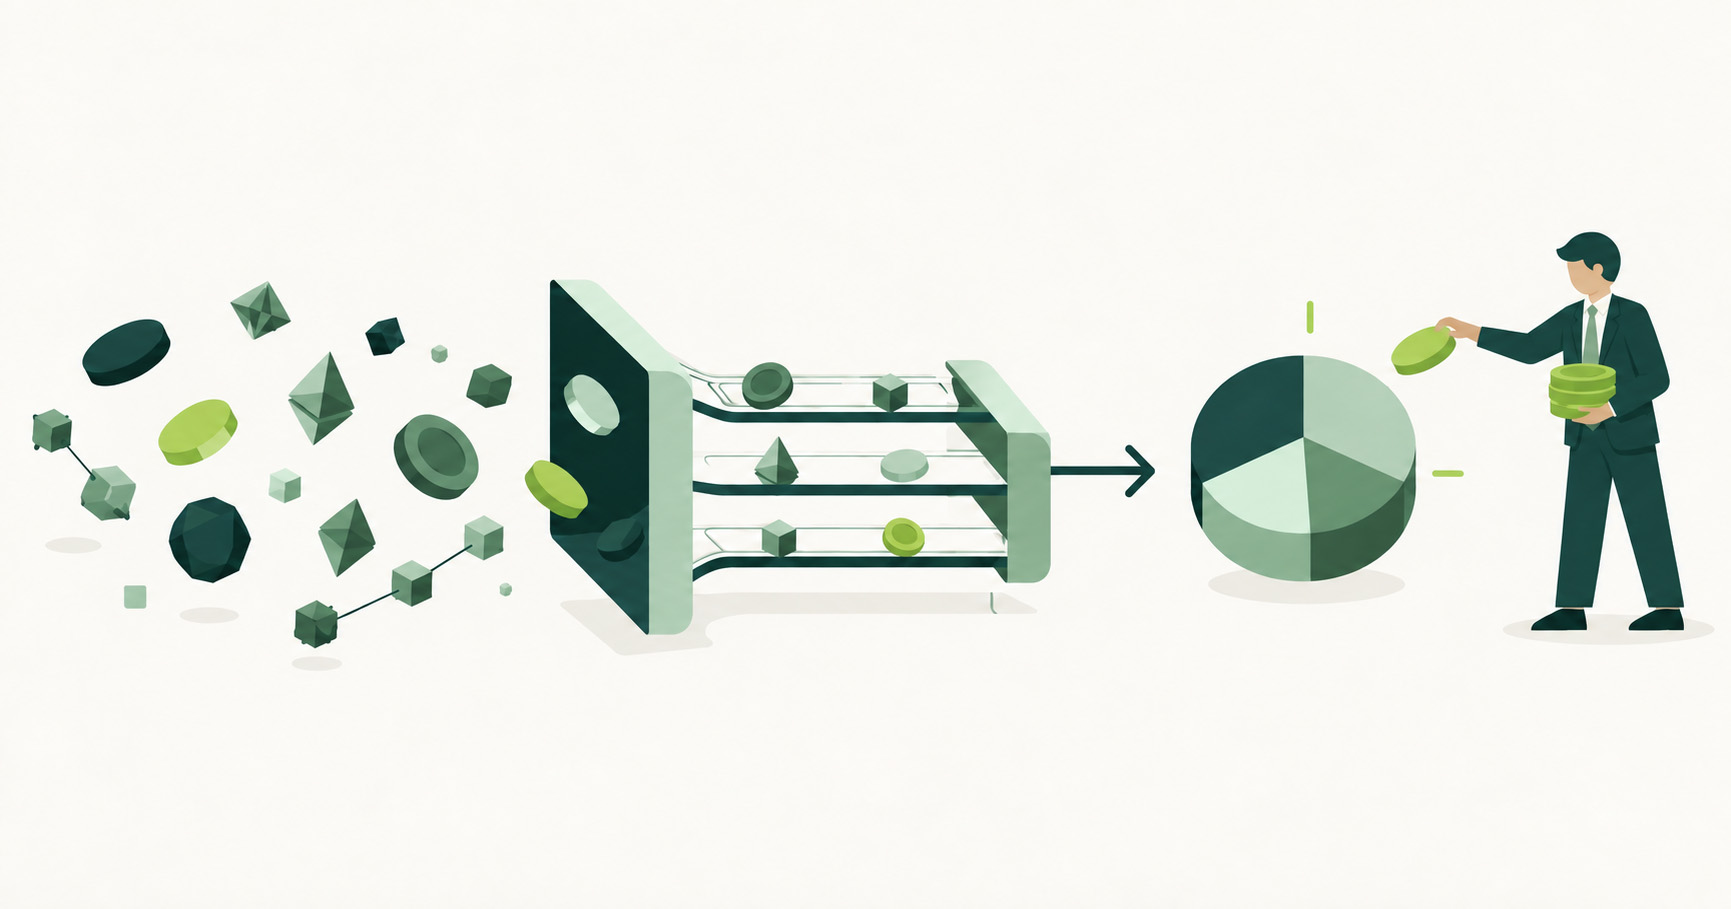
The fund's manager takes the rest of the investment process off your hands, decides the composition of the portfolio and executes the transactions. In return for the investment, the participant receives participations in the fund, also called shares, and not the crypto itself. As a participant you decide whether and when to subscribe or redeem, within the dates the fund provides for, while the manager takes care of everything else.
Whether a fund is the right route depends on a few preferences, such as: the time you want to spend on it, the knowledge you have, and the amount you want to invest.
How a crypto fund is structured
As an example, Hodl's funds are based in Gibraltar. There, a crypto fund is typically a private limited company, set up as an alternative investment fund and regulated by the Gibraltar Financial Services Commission. Participants contribute capital, the manager invests it according to a defined strategy, and the value of a participation moves with the value of the fund's assets.
Two things follow from that structure. The assets are held collectively, so you cannot point to a specific holding/asset and call it yours. And the fund has its own subscription and redemption dates. In practice these are usually monthly.
The manager works within a mandate: what may be bought, in what proportions, and within what risk limits. That mandate is set out in the fund documents. It is therefore the closest thing to an agreement about what will happen with your money.
What you hand over, and what you get back
You hand over the decisions. When to buy, when to rebalance, which assets belong in the portfolio and which do not. For someone who follows this market closely and enjoys it, that is a loss. For someone who does not, it is precisely the point.
You also hand over the timing of your own entry and exit. Funds usually issue and redeem participations on fixed dates, often monthly. On an exchange you can sell at three in the morning; in a fund you cannot. This works both ways and can turn out well or against you during sharp market moves. It is up to the fund manager to manage that properly.
What you get back is custody, administration and execution. The assets sit in a custody environment built for institutional parties. In a well-structured fund the assets are also held separately from the manager's own company, so that the fund's assets are not part of its balance sheet.
A crypto fund also tends to have a more professional infrastructure. Partly through the knowledge of the team and partly through that infrastructure, it can run trading strategies, automated where appropriate, that are not feasible for an individual. Because the manager specialises in this market, it keeps track of the latest developments and technologies, which takes that complexity off the hands of anyone new to the market. There are of course costs attached to outsourcing this. We come back to those in the next section.
Fund, ETF or buying it yourself: how they differ
These are three different products, and the differences weigh more heavily than the similarities.
Buying it yourself means an account with an exchange or a broker, and then a choice: leave the assets there, or move them to a wallet you control yourself. The first is convenient and makes you dependent on that party. The second gives you control, but also makes you responsible for the right procedures and security practices. Lose your recovery phrase, the password to your wallet, and your assets are permanently out of reach.
An exchange-traded product tracks an asset, usually bitcoin or ether, or in some cases a small basket. You buy it through your existing broker, it trades throughout the day, the costs are low and there is no minimum investment. What you do not get is active management: a product like that follows its index and makes no choices.
There is a difference between Europe and the United States here that is often skipped over. In the US, spot ETFs on bitcoin and ether exist. In the European Union they cannot take the same form, because a UCITS fund may not invest in a single asset and crypto is not on the list of eligible assets. A European investor therefore buys an ETP or an ETN in practice, from providers such as 21Shares, VanEck or ETC Group. Those are not fund participations but debt instruments, issued under the law of the country of issue. Economically it resembles an ETF; legally it is something else, and that difference lies mainly in who your counterparty is.
A crypto investment fund with an active mandate does make those choices. That is the difference you pay for. These funds each have their own strategy and can be directional or non-directional. Depending on your preferences you choose the fund that suits you, and the manager executes that strategy against fees agreed in advance.
There is also a practical distinction. An exchange-traded product is open to anyone with a brokerage account. Crypto funds of this kind are not: they carry a minimum initial investment, in our case €100,000 or the US dollar equivalent.
When buying it yourself makes more sense
There are four situations in which a fund is not the obvious answer.
When the amount is below the minimum. A fund with an entry threshold of €100,000 is not a smaller version of itself for €10,000. Below that level the question does not arise, and an exchange or an exchange-traded product is the practical route.
When you only want bitcoin, and you want to hold it. A single asset held for the long term does not call for an active manager. You would be paying for portfolio decisions you have already decided not to make. Direct ownership or an exchange-traded product is cheaper and does the same thing.
When you want to hold the keys yourself. Self-custody is a deliberate choice with a real argument behind it: no third party can freeze, lose or misappropriate what you hold yourself. That argument does not disappear because a fund uses professional custody. If holding your own assets is the reason you are in this market, a fund removes exactly what you came for.
When you want to trade actively yourself. A fund with monthly subscription and redemption is the opposite of a trading account. Anyone who wants to react to a market move within the hour does not belong in a fund, and that is not a criticism of either.
When a fund is the better choice
There are four situations in which the fund route is the more logical one.
When you do not have the time. The crypto market runs around the clock and moves on news that arrives at inconvenient hours. Following it properly can take up a fair amount of time. A fund’s analysts take that work off your hands.
When you do not have the knowledge, and do not want to build it. Choosing between assets, judging a protocol, understanding how a position is constructed: that takes study. Anyone who wants exposure to this market without becoming a specialist in it is buying in expertise, and that is what a manager provides.
When you do not want to arrange custody yourself. Storing your own crypto means procedures, (offline) backups and the discipline to keep to them for years. One mistake is permanent. In a fund the assets sit with a custodian built for institutional parties and the keys are managed by people who do nothing else.
When you are looking for a specific strategy. Directional, market neutral (not dependent on which way the market moves), long-only, a mandate with defined risk limits: these are choices you cannot reproduce with a single purchase on an exchange. A fund can be a straightforward way to make such a strategy part of your investment portfolio.
Beyond these there are plenty of other specific reasons, which partly overlap with the points above. Consider the case where you already hold bitcoin but want to place an additional amount, or part of that position, in a market neutral fund for a more stable return, in order to counter the swings. Or the case of extending your bitcoin position with exposure to a broader portfolio.
What to look at when you assess a fund
If a fund does fit, the fund documents answer more than a website does. Five questions are worth asking first.
Who holds the assets, and are they separate from the manager? The fund's assets should not be part of the manager's balance sheet. Ask who the custodian is, how the keys are managed, and how many people are required to authorise a transaction.
What exactly does it cost, and what does “return” mean here? A management fee as a percentage of assets and a performance fee on the gain are common; 2 percent and 20 percent is a widely used combination. Check as well whether the returns being communicated are before or after costs.
When can you get out? Monthly issue and redemption without a lock-up is very different from a fund with a multi-year commitment. Ask also what happens if many participants want to exit at once.
What is the regulatory position, and in which jurisdiction? This is where the differences between funds are largest, and where the wording matters. A fund can be registered with a supervisor without being subject to ongoing supervision, and it can be regulated, which is something else. Our internationally available funds are based in Gibraltar and regulated by the Gibraltar Financial Services Commission; our Dutch funds are registered with the AFM under an exemption, which is not a licence and does not mean there is ongoing supervision. Neither status is a seal of approval, and it is worth knowing exactly which one applies and what it covers.
What do the documents say? The Essential Information Document and the Information Memorandum set out the mandate, the risks and the costs. They read less pleasantly than a website, and they are the only place where the actual agreement is written down.
Conclusion
A crypto investment fund and buying it yourself are not the better and the worse version of the same thing. They are two routes with a different division of work, control and responsibility. Anyone who follows this market themselves and wants to hold their own keys is better off getting on with it directly. For anyone who wants to allocate a serious amount without arranging self-custody, market research, execution and administration, a fund can be a good solution.
We manage crypto funds ourselves, from Gibraltar and the Netherlands, so we are not a neutral party here. That is exactly why it matters that you weigh this up yourself and set the advantages of a fund against its drawbacks. If you have questions about investing in a crypto fund after reading this article, please get in touch. We would be glad to help.